When disaster strikes an HOA community, reconstruction responsibility depends on governing documents, insurance coverage, reserve funds, and board decisions. This guide explains who pays, who manages insurance claims, and how disaster recovery unfolds in Texas HOAs.
When a storm tears through a neighborhood or floodwaters rise fast, the question comes quickly and doesn’t go away: Who is responsible for reconstruction after disaster in an HOA? It sounds simple. It isn’t. Between insurance claims, reserve funds, special assessments, and the authority of each board member, the answer depends on legal documents and state law as much as it does on physical property damage.
Texas alone experienced 16 separate billion-dollar weather and climate disasters in 2023, according to NOAA’s National Centers for Environmental Information. Those events included hurricanes, floods, hail, and severe storms that left thousands of properties with significant damage. In communities governed by homeowner associations, disaster recovery becomes a layered process. Ownership lines blur. Coverage limits surface. And disagreements sometimes follow.
So here’s what actually determines who is responsible for reconstruction after disaster in an HOA, and why it matters.
Who is responsible for reconstruction after disaster in an HOA
The starting point is never guesswork. It is always the governing documents. Declarations, bylaws, and covenants outline the allocation of responsibility between the association and individual owners. If disaster strikes and roofs collapse, exterior walls crack, or shared amenities suffer structural failure, those documents define the financial burden.
In most condominium and multi-family HOA structures, common areas fall under association responsibility. That typically includes structural framing, exterior walls, roofs, stairwells, foundations, and shared systems. Interior finishes, personal property, and certain unit components remain the owner’s obligation. However, limited common elements such as balconies or assigned exterior fixtures may sit in a gray area.
Here’s how responsibility generally breaks down:
| Damage Category | Typical Responsible Party | Governing Influence |
| Structural common areas | HOA | Declaration and master policy |
| Interior unit finishes | Individual owner | Unit deed and bylaws |
| Shared amenities | HOA | CC&Rs |
| Limited common elements | Varies | Defined in governing documents |
| Personal belongings | Individual owner | Homeowner policy |
Note: Although these are general guidelines, your specific Association’s CC&Rs and Governing Documents take precedence over standard rules, so be sure to review them carefully.
The language inside these documents determines who is responsible for reconstruction after a disaster in an HOA. Texas law does not automatically shift that burden; it enforces the contractual obligations already established.
Insurance Claims and Coverage Boundaries
Insurance often determines whether reconstruction moves quickly or stalls. Associations typically carry a master policy covering common areas. Individual owners carry policies for interior contents and improvements. After natural disasters such as hurricanes and floods, both policies may activate simultaneously.
According to FEMA’s Public Assistance Program data, insurance remains the primary funding source for private property repair following declared disasters. FEMA assistance supplements but does not replace insurance coverage. That distinction matters when an HOA begins disaster response efforts.
When significant damage occurs, the board member leadership team must document property damage thoroughly. Insurance adjusters review evidence, evaluate structural reports, and assess policy limits. If deductibles exceed reserve funds, boards may consider special assessments to bridge the gap.
Here’s how funding sources often interact:
| Funding Source | Applies To | Typical Limitations |
| HOA master insurance | Common areas (roofs, lobbies, shared structures) | Deductibles, exclusions |
| Owner insurance (HO-6) | Interior unit (walls-in, personal belongings, liability) | Policy caps |
| Reserve funds | Capital repair | Limited balance |
| Special assessments | Community wide | Requires an approval process |
Deductible allocation clauses often become the most misunderstood component of reconstruction funding. Many HOA master policies contain provisions specifying whether the deductible applies per building, per occurrence, or per unit. Some declarations require individual owners to contribute proportionally toward the deductible if damage originates from within their unit.
Others assign the entire deductible to the association, even if a single structure suffers loss. The allocation language matters because storm-related deductibles in Texas can reach significant percentages of insured value, especially for hurricane or wind coverage.
If not addressed clearly in governing documents, deductible disputes frequently surface during disaster recovery. Understanding these clauses before disaster strikes reduces financial shock and conflict.
If my condo is destroyed in a catastrophic event, the owner typically relies on individual insurance coverage for interior rebuild. The association addresses structural shell repair. That division explains why understanding who is responsible for reconstruction after disaster in an HOA is so important before disaster strikes.
What Happens If My Condo Is Destroyed?
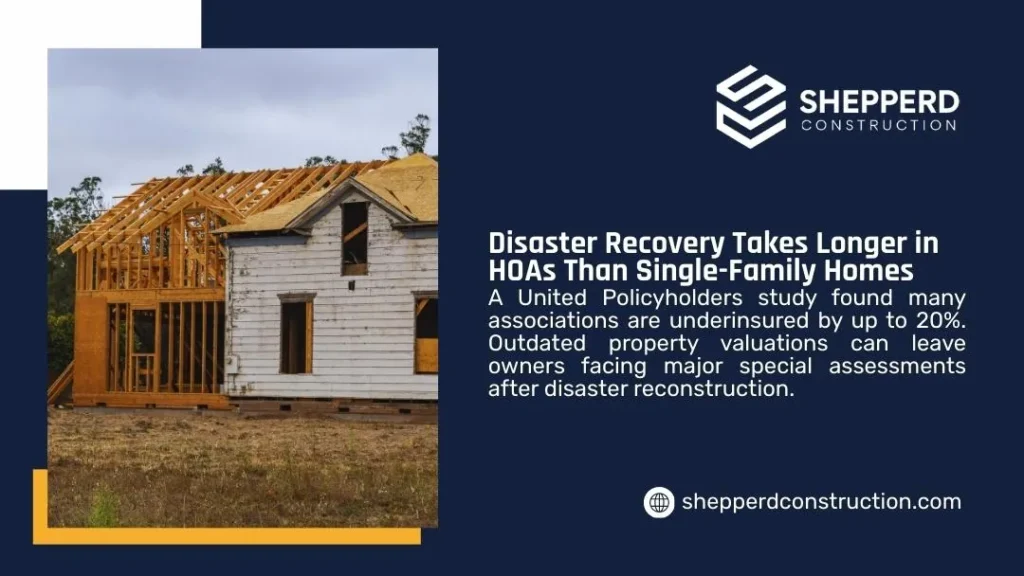
When a unit is destroyed, whether by fire, flood, or severe storm, responsibility splits between structural restoration and interior reconstruction. Boards and owners dealing with a multifamily fire loss can follow our guide to rebuilding a fire-damaged apartment building, which covers each phase from the first site visit to final inspection. In most Texas condominium HOAs, the association rebuilds the exterior shell and common structural components. When fire is the cause, the same split shapes how fire damage reconstruction is scoped for a multifamily building.
That includes framing, roofing systems, exterior walls, and shared utilities. Individual owners are generally responsible for interior finishes, cabinetry, flooring, appliances, and personal belongings.
Insurance policies dictate how that process unfolds. The HOA files claims under the master policy for structural rebuild. Once the claim is underway, owners often ask about a realistic timeline for rebuilding the building, which we cover in a separate Texas guide. The unit owner files under their personal policy for interior improvements and contents. Timing becomes critical.
Delays in insurance adjustment can slow reconstruction across the entire building, particularly when multiple units sustain significant damage. Coordination between carriers, contractors, and board leadership determines whether recovery takes months or stretches into years.
If insurance proceeds prove insufficient to restore the building to its prior condition, governing documents may authorize special assessments or proportional contributions from affected owners.
In rare cases, declarations allow termination of the condominium regime if reconstruction costs exceed a defined threshold. That outcome remains uncommon but legally possible. For that reason, owners should review governing documents and coverage limits long before asking what happens if my condo is destroyed.
Reserve Funds, Special Assessments, and Fiduciary Duty
Reserve funds exist for predictable capital repairs. They are not designed to absorb catastrophic rebuilding unless specifically structured that way. The report shows that nearly 70% of HOAs nationwide have underfunded reserves. That statistic alone complicates disaster recovery.
A board member has a fiduciary duty to manage reserve funds prudently. For large projects outside a disaster, our Texas HOA guide to reserve-identified repairs covers how to plan the work the study has already flagged. If disaster recovery exceeds reserves and insurance payouts, the board may initiate special assessments. In Texas, such assessments often require member notice and sometimes a vote, depending on governing documents. Boards preparing that step can find voting thresholds, timelines, and owner rights laid out in our guide to Texas HOA reconstruction assessment rules.
Financial strain during disaster recovery frequently triggers dispute resolution proceedings. Owners may question whether assessments were necessary or whether insurance claims were maximized. Transparent communication reduces conflict and protects the board’s authority.
Common Areas Versus Individual Units
Responsibility after property damage depends less on emotion and more on classification. In every HOA, assets fall into legal categories that determine financial and reconstruction duties. When disaster strikes, the dividing line between common areas and individual units shapes who authorizes repairs, who files insurance claims, and who ultimately pays. The governing documents define these categories, but understanding how they function in real scenarios prevents confusion during disaster recovery. Balconies sit right on that dividing line, which is why the question of who pays for balcony structural failure repairs so often turns into a dispute between a board and individual owners.
Common areas generally include structural systems and shared property essential to the integrity of the community. Individual units contain components that serve only one owner. Between those two sits a third category that often creates tension: limited common elements. These are shared in ownership but restricted in use, which can complicate responsibility when significant damage occurs.
The table below outlines how these distinctions typically operate in Texas HOA communities.
| Property Classification | Typical Examples | Reconstruction Responsibility | Insurance Source | Key Consideration |
| Common Areas | Roof structures, exterior walls, foundations, structural framing, shared plumbing lines, parking areas, and pools | HOA Board | HOA master policy | Defined in declaration and CC&Rs |
| Limited Common Elements | Balconies, assigned parking spots, exterior doors, and certain HVAC components | Varies by governing documents | Often HOA policy is sometimes shared | Responsibility language varies significantly |
| Individual Units | Interior drywall, flooring, cabinetry, appliances, fixtures | Individual Owner | Owner’s HO-6 or condo policy | The owner maintains the interior components |
| Personal Property | Furniture, electronics, décor | Individual Owner | Owner’s personal policy | Not covered under the HOA policy |
Although this framework appears straightforward, real-world scenarios rarely follow clean lines. For instance, if wind compromises roofing material and water enters multiple units, the structural failure originates in a common element. The HOA typically repairs the roof. Interior remediation inside each unit, however, may fall to individual owners unless the governing documents specify otherwise or negligence is established.
Disputes most often arise around limited common elements. A balcony attached to a unit might appear private, yet it could legally qualify as a common structural component. That distinction affects both insurance claims and deductible allocation. When insurance deductibles are substantial, determining whether the cost is absorbed by the association or passed proportionally to owners can significantly impact financial stability.
Understanding these classifications before an event of a disaster occurs allows both board members and owners to anticipate their obligations. Clear documentation and proactive review of governing documents reduce confusion and support smoother disaster response when reconstruction becomes necessary.
Disaster Response and Local Coordination
When disaster strikes, reconstruction does not begin immediately. Safety comes first. Debris removal, hazard containment, and emergency stabilization typically precede full rebuild. Local authorities may mandate inspections before occupancy resumes.
The Texas Division of Emergency Management coordinates disaster response in declared events, while FEMA may offer federal support. However, HOAs retain responsibility for their property. That responsibility includes hiring correctly, which starts with understanding who rebuilds a property after damage once mitigation crews finish their work. Municipal intervention rarely replaces association duties.
Effective disaster recovery follows a sequence: assessment, documentation, insurance engagement, financial planning, contractor selection, and phased reconstruction. Skipping steps can lead to prolonged disputes and delayed completion.
Immediate repair differs substantially from full reconstruction or structural remediation. Immediate repair focuses on stabilization, tarping roofs, boarding openings, and removing hazards. Full reconstruction restores damaged components to their prior condition once funding and scope are confirmed.
Structural remediation goes further. It addresses hidden deficiencies, compromised framing, and envelope failures uncovered during investigation. In HOA environments, confusing these stages can result in incomplete recovery and recurring damage. Proper sequencing protects both structural integrity and financial stability.
Dispute Resolution in Post-Disaster Reconstruction
Disagreements often surface when reconstruction timelines stretch or assessments rise. Governing documents outline dispute resolution pathways, including mediation or arbitration. Clear documentation during insurance claims reduces liability risk and strengthens the association’s position.
Communication remains the stabilizing factor. Regular updates about insurance claims, repair scopes, and financial obligations build trust. Without transparency, tension grows.
Contractor Selection and Community Protection
Large-scale reconstruction requires technical expertise beyond routine maintenance. Structural failures, waterproofing systems, and envelope restoration demand qualified oversight. Boards should evaluate contractor experience with multi-family and HOA environments, not just general residential repair.
Communities across Texas often rely on firms experienced in regional climate patterns. Associations in Central Texas may work with Reconstruction Contractors Austin, while North Texas communities turn to Reconstruction Contractors Dallas or Reconstruction Contractors Fort Worth. South Texas regions frequently seek Reconstruction Contractors San Antonio familiar with hurricane and flood exposure.
Selecting a contractor involves reviewing prior projects, verifying insurance, and confirming compliance with HOA governance requirements.
The Texas Context: Why Geography Matters
Texas consistently ranks among the states with the highest frequency of billion-dollar disaster events, according to NOAA climate records. Coastal exposure, expansive clay soils, and extreme heat cycles create stress on building envelopes even before a storm arrives. That reality influences both insurance rates and reconstruction strategy.
Understanding who is responsible for reconstruction after disaster in an HOA requires awareness of these regional conditions. Reserve studies, insurance evaluations, and long-term maintenance plans should reflect environmental risk.
Protecting Community Stability Before the Next Event
Communities that recover well are the ones that prepare early and act decisively. When reconstruction after disaster becomes necessary, execution matters as much as funding. Structural integrity, waterproofing systems, and long-term performance cannot be left to guesswork.
If your HOA board or property management team is evaluating post-disaster reconstruction, consult professionals who understand both the technical complexity and the governance structure of association communities. Shepperd Construction works alongside boards, engineers, and property stakeholders across Texas to deliver disciplined, compliant, and durable reconstruction solutions.
Learn more about our experience and capabilities or explore our Reconstruction Services to see how we support HOA communities throughout Texas. If your association is facing immediate recovery decisions, contact our team to discuss next steps with clarity and confidence.